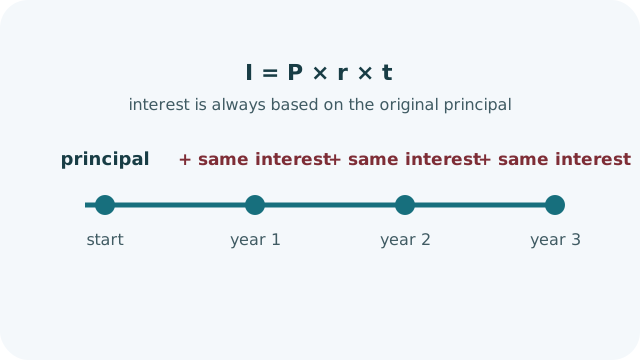
The result grows by the same amount each year because interest is not added to the base. It can be used to check a stated simple-interest example. Actual credit may include amortizing payments, daily accrual, compounding, fees and differing day-count rules.
Practical use: People usually open this page when they need to calculate non-compounding interest from principal, annual rate and time without building a spreadsheet for a single question. Simple interest applies the original principal throughout the period. It is useful for teaching and for agreements explicitly written on a simple-interest basis, but it does not match products that compound or use daily balances. For a real decision, calculate a central case and then change the most uncertain input to a reasonable lower and upper value. Seeing that range is often more informative than treating one rounded answer as permanent.
A useful result should be repeatable: keep the original inputs, unit choices and relevant date beside the interest and total amount. If a second source uses another convention, reconcile that difference before comparing the numbers.
When sharing the answer, include a short label such as “interest and total amount from the stated inputs.” That label keeps the number attached to its meaning. It also prevents a reader from mistaking a converted value, model output or planning estimate for a direct observation.
Scope: It does not compound, amortize payments or include fees and taxes.